Welcome to Victory Mortgage

GET STARTED

Welcome to Victory Mortgage


GET STARTED

Calculate Your Costs

Use the customize button for more accuracy
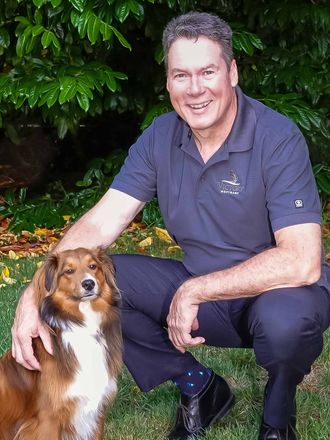
Darrell McCollom. Mortgage Broker.

Victoria's mortgage expert for the last 25 years.

Darrell McCollom

I'm Darrell, thanks for visiting my website, I'm an Independent mortgage broker and founder of Victory Mortgage with our office located at 446 Goldstream Avenue in Colwood. I'd love to work with you to help you get the best mortgage.

Getting the best mortgage is looking beyond just the best rate, it includes understanding different mortgage products and how they impact your long term financial goals. I bring a commitment to finding you the best mortgage despite a rapidly changing market conditions. I work with integrity, honesty and education to help coordinate your unique financial requirements to the best product to save you money and time.

In my spare time I enjoy time with my family. I have a passion for aviation history and history in general. Friends and family are very important to me and I enjoy sharing as much time as I can with them in this beautiful city.

I understand mortgage financing deeply and invite you to use my expertise and experience to your advantage. Let's get together and talk a bit so I can really get to know your situation and provide tailored mortgage advice.

Nice things people have said about working with me.

Finding the best mortgage can be frustrating. It doesn't have to be when you follow my 3 step plan.

Get started right away

The best place to start is to connect with me directly. My commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise. I'll outline the best mortgage products available with your needs in mind.

Proceed with confidence

My goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, I'm available to answer any questions for as long as you need a mortgage. I've got you covered.

Get started by completing my online mortgage application.

APPLY NOW

I'll let you know exactly where you stand so you can proceed with confidence.

Go ahead and book a call with me.

BOOK NOW

Let's run some numbers

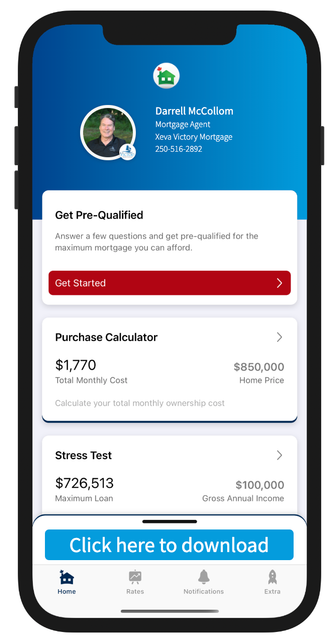
Download my app

What you can do with my app


Calculate your total cost of owning a home

Estimate the minimum down payment you need

Calculate Land transfer taxes and the available rebates

Calculate the maximum loan you can borrow

Stress test your mortgage

Estimate your Closing costs

Compare your options side by side

Search for the best mortgage rates

Email Summary reports (PDF)

Use my app in English, French, Spanish, Hindi, and Chinese
DOWNLOAD APP

Everything you need, all in one place

As a trusted mortgage provider, let me help you with these services.

Click through any of the services to learn more

Mortgage articles to keep you informed.
By Darrell McCollom • November 11, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
By Darrell McCollom • November 4, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
By Darrell McCollom • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Show More